IRS Offer in Compromise Success Rate: What the Data Shows
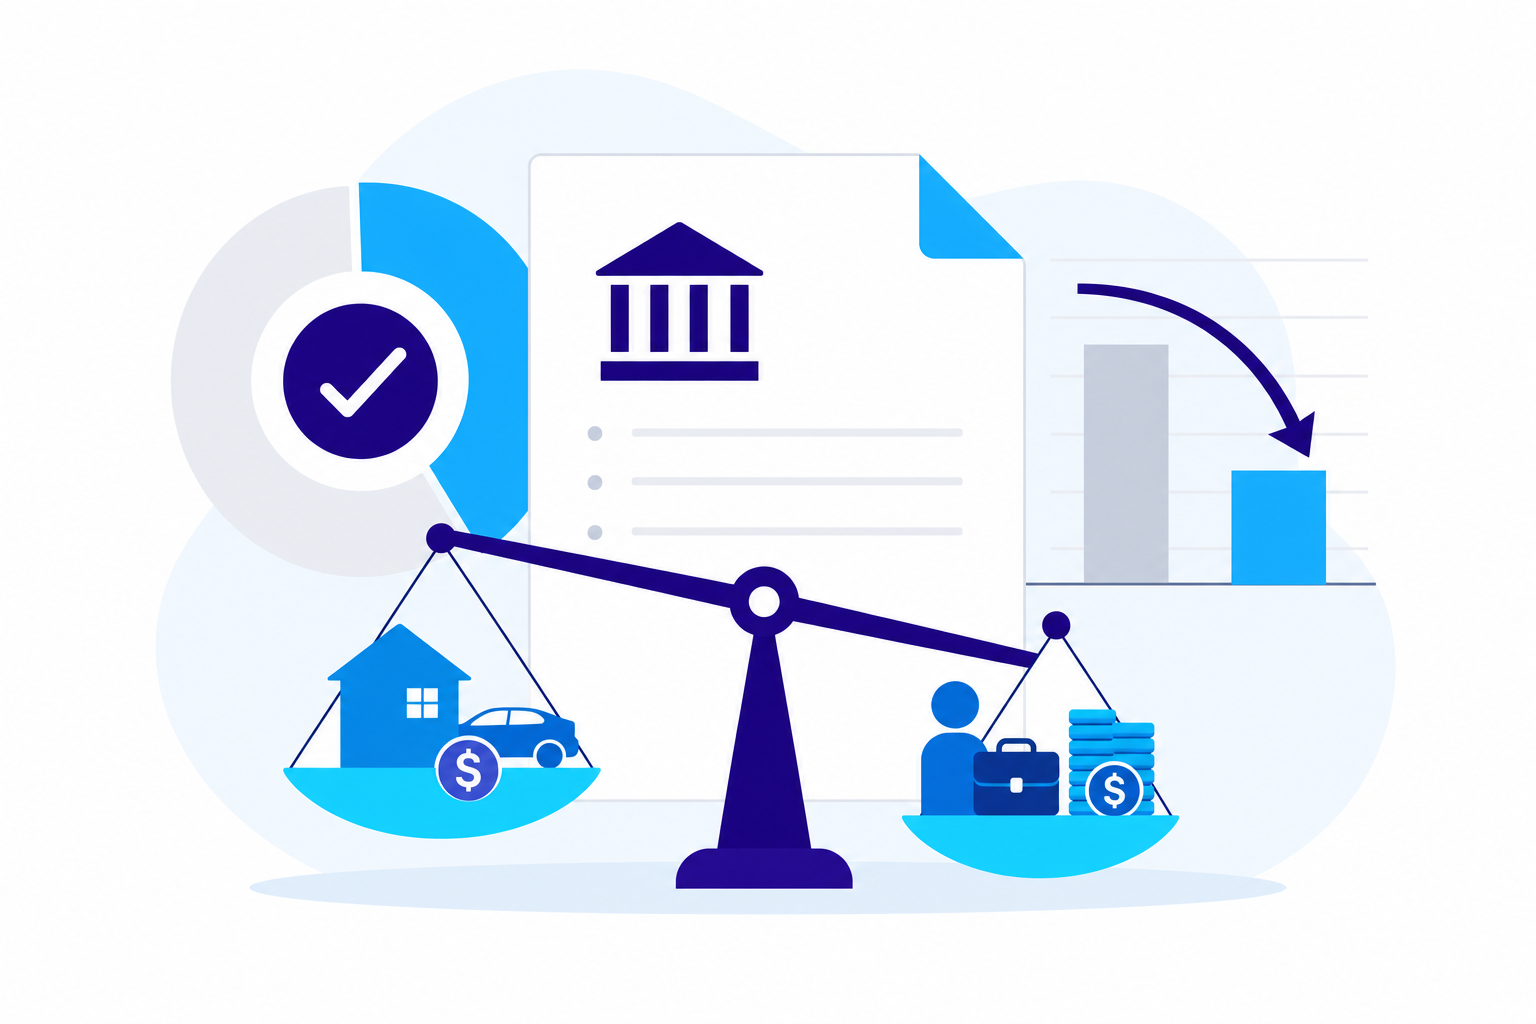
The IRS offer in compromise success rate has held in the low-to-mid teens as a share of all applications received in recent fiscal years, with accepted offers averaging a 59% reduction in the original tax debt. Whether your offer succeeds depends almost entirely on how your Reasonable Collection Potential (RCP) compares to what you owe. Raw acceptance statistics tell you how the program performs on average. The RCP formula tells you whether you personally qualify.
What Do IRS Offer in Compromise Success Rate Numbers Actually Mean?
Acceptance rate figures are easy to misread. A rate in the low-to-mid teens sounds discouraging, but it includes every application the IRS received, including ones submitted by taxpayers who were never eligible, ones returned for missing paperwork, and ones where the offered amount was far below what the IRS could realistically collect.
In fiscal year 2024, the average accepted offer in compromise resulted in a 59% reduction in the taxpayer's original tax debt. That figure matters more than the raw acceptance rate. It tells you that when the IRS does accept an offer, it is accepting meaningful reductions, not token discounts.
What the acceptance rate does not tell you is how many applications were returned without review. A returned application is not the same as a rejection. It does not tell you how many applicants were ineligible from the start. And it does not tell you whether applicants who worked with a qualified representative fared better than those who applied alone.
The more useful question is not "what percentage of offers get accepted?" but "does my financial profile support a viable offer amount?" The IRS uses a specific formula to answer that question. Understanding that formula is what lets you assess your own odds before you spend months in the application process.
Looking back, acceptance rates in 2020 and surrounding years remained in the low-to-mid teens, and accepted offers consistently produced substantial reductions for taxpayers whose RCP fell below their total debt. The trend has been stable enough that the acceptance rate percentage alone should not be the deciding factor in whether you apply.
Returned vs. Rejected: Why the Distinction Changes Your Strategy
Many offers that never reach acceptance were never fully reviewed. The IRS distinguishes between two outcomes that taxpayers often treat as the same thing.
A returned offer means the IRS sent your application back without reviewing it on the merits. Common reasons include missing forms, unfiled tax returns, failure to include the required initial payment, or an active bankruptcy proceeding at the time of submission. A returned offer is a procedural failure, not a substantive one. You can correct the problem and resubmit.
A rejected offer means the IRS reviewed your financials and concluded your RCP exceeded your offer amount. The IRS determined it could collect more through other means, such as installment agreements or levy action. A rejection is a substantive decision, and it carries a different set of options.
When an offer is rejected, you have the right to appeal to the IRS Office of Appeals within 30 days of the rejection date. Appeals gives your case fresh eyes, reviewed by an officer who was not involved in the original decision. If your offer was rejected because the examiner miscalculated your RCP or applied the wrong expense standards, an appeal can correct that.
Understanding which outcome you received shapes your next move. A return calls for correcting paperwork. A rejection calls for evaluating whether the IRS's RCP calculation was accurate. For a detailed walkthrough of the appeals process, see How to Appeal an IRS OIC Rejection: The Form 13711 Roadmap.
Why Do Business Offers Have Different Acceptance Rates Than Individual Offers?
Business and individual taxpayers approach the Offer in Compromise (OIC) program with different financial structures, and the IRS evaluates them differently. Business offers, filed under the Business Master File (BMF), historically show lower acceptance rates than individual offers filed under the Individual Master File (IMF). The reasons are structural.
A business with accounts receivable may dispute whether the IRS's assumed collection rate applies to that balance. Equipment and inventory valuations are similarly contested. Business income fluctuates in ways that complicate the future income component of the RCP calculation, and business taxpayers often carry payroll tax liabilities, which the IRS treats with less flexibility than income tax debt.
The consequences of a rejected business offer are significant. According to Taxpayer Advocate Service research, for rejected or returned business offers, the median amount originally offered was more than five times the amount the IRS eventually collected. That gap suggests the IRS frequently overestimates what it can collect from business taxpayers, and that many rejected business offers represented reasonable settlements the IRS declined.
On the compliance side, the same TAS research found that 91 percent of business taxpayers remained in filing compliance for five years following an accepted offer. That figure matters because the IRS monitors compliance after acceptance. If you default on the five-year compliance requirement, the offer can be revoked and the original debt reinstated. For more on that risk, see Why IRS Offers in Compromise Get Revoked: 5-Year Rule.
If you own a business and are considering an OIC, the complexity of the BMF process is one reason professional representation tends to add more value than it does for straightforward individual cases. For broader context on IRS debt relief options, the IRS Debt Relief Programs resource library covers the full range of resolution paths available to both individuals and business owners.
How Does the IRS Calculate What It Will Accept? The RCP Formula Explained
The IRS will not accept an offer simply because you cannot pay in full right now. It will accept an offer only if the amount you propose equals or exceeds your Reasonable Collection Potential (RCP), the IRS's estimate of the most it could realistically collect from you through other means.
RCP has two components: net asset equity and future income.
Net asset equity is the value of everything you own that the IRS could seize and sell, minus any secured debt against those assets. The IRS applies a quick-sale discount below fair market value, because forced asset sales rarely bring full price. Your home equity, bank balances, retirement accounts, and vehicles all factor in.
Future income is the portion of your monthly income that exceeds your allowable living expenses (ALE). The IRS sets ALE standards nationally for categories like food, clothing, and personal care, and uses local standards for housing and transportation. These standards cap what the IRS will accept as necessary living expenses, regardless of what you actually spend. Your disposable income after those allowances is multiplied by either 12 or 24, depending on your payment method, to produce the future income component.
Your RCP equals net asset equity plus future income. Your offer must meet or exceed that number.
That reduction is possible precisely because RCP often falls well below the total balance owed, especially for taxpayers with limited assets and modest disposable income after allowable expenses.
The IRS Pre-Qualifier Tool can help you estimate your RCP before you file. You enter financial data and it returns an estimated minimum offer amount. Per legalclarity.org and unclekam.com, the tool does not account for every variable in the RCP calculation and should not be treated as a definitive eligibility determination. Use it as a starting point, not a final answer. For a more detailed walkthrough of how to build an accurate RCP calculation, see How to Calculate Your RCP for an IRS Offer in Compromise.
Scenario: Suppose your net asset equity totals a set amount and your monthly income after IRS-allowable expenses leaves a fixed surplus. For a lump-sum offer, you multiply that monthly surplus by 12 to get the future income component, then add it to your net asset equity. The resulting total is the floor for an acceptable offer, regardless of how much you owe in total.
What Are the Qualifications for an Offer in Compromise?
The IRS will not review an offer on the merits until you clear a set of threshold eligibility requirements. Failing any one of them results in a returned application, not a rejection.
To qualify, you must meet all of the following conditions:
- All required federal tax returns are filed. The IRS requires at least the last six years of returns to be current before it will process an offer. Unfiled returns are the single most common reason applications are returned without review.
- You are current on estimated tax payments. If you are self-employed or otherwise required to make quarterly estimated payments, those must be up to date at the time you submit and throughout the review period.
- Business owners must be current on federal tax deposits. If you have employees, all required payroll tax deposits must be current.
- You are not in an active bankruptcy proceeding. The IRS cannot process an offer while a bankruptcy case is open. You must wait until the case is closed or dismissed.
- You have a legitimate basis for the offer. Most offers are filed under Doubt as to Collectibility (DATC), which means your RCP is less than your total tax debt. Other grounds include Doubt as to Liability (you dispute the underlying tax assessment) and Effective Tax Administration (you could technically pay but doing so would cause economic hardship or be inequitable). DATC is by far the most common basis.
Meeting these conditions does not guarantee acceptance. It only clears you for review. The IRS will then evaluate your RCP against your offer amount and make a determination based on the numbers.
One condition that continues after acceptance is equally important: you must remain in full filing and payment compliance for five years following the date the IRS accepts your offer. A single missed return or unpaid tax bill during that window can void the agreement and reinstate the original debt in full.
How to Calculate and Submit Your Offer in Compromise: Step by Step
Preparing a complete, accurate application is the most direct way to avoid a procedural return and keep your offer moving forward. Follow these steps in order:
File all required federal tax returns for at least the last six years. [S1] The IRS will not process your offer until your filing history is current. Pull your IRS transcript to confirm which years are on record before you submit anything.
Confirm current payment compliance. [S2] If you owe estimated taxes, make sure the current quarter is paid. Business owners must verify that all required federal tax deposits are current. The IRS checks compliance at submission and again throughout the review period.
Verify that no active bankruptcy proceeding is open. [S3] If a case is pending, the IRS cannot process the offer. Wait until the bankruptcy is resolved before filing.
Calculate your RCP. [S4] Total your net asset equity using the IRS quick-sale value standard, then add your future income component. Use the IRS's published ALE standards to determine your allowable monthly expenses before calculating disposable income. The IRS Pre-Qualifier Tool can give you a working estimate, but the numbers you use on your actual application must come from Form 433-A (for individuals) or Form 433-B (for business owners). For business-specific guidance on that form, see Submitting an OIC as a Small Business: Form 433-B Explained.
Determine the future income multiplier based on your payment method. [S5] If you plan to pay in a lump sum within five months, multiply your monthly disposable income by 12. If you plan to pay in periodic installments over six to 24 months, multiply by 24. The periodic payment option produces a higher minimum offer amount.
Select your payment method and prepare the required initial payment. [S6] Lump-sum offers require a down payment submitted with the application. Periodic payment offers require the first installment payment at submission. Low-income taxpayers who meet the IRS's criteria may qualify for a fee waiver; otherwise, a non-refundable application fee applies.
Once submitted, the IRS review process takes time. A historical Government Accountability Office report from 2006 noted that single offers averaged about 5.8 months to process, while repeat offers averaged around two years. Current timelines may differ, but complex cases or resubmissions consistently take longer. If the IRS does not act on your offer within two years of the date it was received, the law treats the offer as accepted by operation of statute. That two-year clock is one reason it pays to submit a complete, accurate application the first time.
When Does Professional Help With an Offer in Compromise Make Sense?
Self-preparing an OIC is possible, but the margin for error is narrow. A miscalculated RCP, a missing form, or a single unfiled return can result in a return without review, months of lost time, and a restarted clock.
Professional representation adds the most value in three situations. First, if your financial picture is complicated, meaning you own a business, hold real estate, have retirement accounts, or earn irregular income, the RCP calculation involves judgment calls that the IRS Pre-Qualifier Tool cannot fully resolve. Second, if a prior offer was rejected, an experienced representative can identify whether the examiner's RCP calculation was accurate and build a documented case for appeal. Third, if you owe payroll taxes, the IRS applies stricter standards, and the procedural requirements are more demanding.
Wolf Tax is a tax resolution firm led by a licensed tax attorney. The firm contacts the IRS directly, investigates your full tax situation, and handles all IRS communications on your behalf from the initial consultation through final resolution. Pricing is flat-fee, quoted per case with monthly payment options, and no hourly billing. The first step is a free consultation to assess whether an OIC is the right path or whether another resolution program fits your situation better.
FAQs
Does the IRS have a 90-day rule for offers in compromise?
There is no single "90-day rule" that governs OIC acceptance. The IRS does review whether it could collect the full liability before the collection statute expires, and it will not accept an offer if it concludes it can realistically do so. The key factor is always your RCP compared to the total debt. Separately, once the IRS mails a rejection letter, you have 30 days to file an appeal with the Office of Appeals.
Does the IRS offer in compromise success rate differ by state?
Your state of residence does not determine whether the IRS accepts your offer. The OIC program operates under federal rules applied uniformly to all applicants. What does vary by location is the IRS's local expense standards for housing and transportation, which feed into the RCP calculation. A taxpayer in a high-cost city may have higher allowable living expenses, which can lower their calculated RCP and potentially strengthen an offer.
Can you reapply after an offer in compromise is rejected?
Yes. A rejection is not permanent. You can submit a new offer at any time, provided you remain in filing and payment compliance. Before resubmitting, review why the original offer was rejected. If the IRS's RCP calculation was the basis, gather updated financial documentation, correct any errors, and recalculate before filing again. You also have the right to appeal a rejection to the IRS Office of Appeals within 30 days of the rejection date.
Does filing an offer in compromise stop IRS collection actions?
Filing an OIC generally pauses most IRS collection activity while the offer is under review. The IRS typically suspends levies and garnishments during the review period. However, existing liens remain in place, and the IRS can still take action in certain circumstances. Confirm the current status of any collection activity with a qualified representative before relying on the review period as protection.
What happens if the IRS does not respond to an offer within two years?
Under federal law, if the IRS does not accept, reject, return, or otherwise act on a submitted offer within two years of the date it was received, the offer is considered accepted by operation of statute. This two-year clock runs from the IRS receipt date, not the postmark date. Keeping proof of the IRS's receipt date is important for any offer that remains unresolved for an extended period.
Conclusion
The IRS offer in compromise success rate in the low-to-mid teens as a share of all applications is a program-wide average, not a prediction for your case. Your outcome depends on one thing above all: whether your RCP falls below what you owe. When it does, the IRS has shown it will accept meaningful reductions.
Before you apply, confirm your filing compliance is current, calculate your RCP using the IRS's ALE standards and the correct income multiplier for your payment method, and use the Pre-Qualifier Tool as a rough check. If your financial situation is complex or a prior offer was rejected, a qualified representative can identify errors in the IRS's calculation that you may not catch on your own.
You May Also Like
These Related Stories
How to Calculate Your RCP for an IRS Offer in Compromise
The IRS 'Get Out of Jail Free' Card: How to Use First-Time Abatement